Fastest Way to Sell a House: Timeline, Costs & Seller Options
Search for the fastest way to sell a house and you’ll find promises measured in days: close in seven, sell in a week, cash by Friday. Some of those timelines are real for some houses. The trouble is that a fast closing depends far less on the route you pick than on what is standing between your particular house and the closing table. A buyer who can pay cash can’t close before a payoff letter arrives. A well-priced listing can attract an offer in two days and still need five weeks to fund. And a perfectly clean file can be stopped cold by an owner nobody can find.
The fastest realistic way to sell a house is usually to a buyer who doesn’t need a loan, when the title is clean and the home can be handed over on time. But speed is set by bottlenecks (financing, appraisal, inspection, title, possession, court steps), so the quickest route is whichever one removes the bottleneck your house actually has.
That’s the practical answer, and it comes with a ranking that changes by situation. This guide is about the ranking: what sets the clock on a home sale, how each route handles each delay, what speed costs in dollars at different points along the curve, and where a seemingly fast option turns out to be slower than a plain listing. If you want the stage-by-stage answer to “how long will mine take,” the guide to how fast you can sell your house walks through the stages. If you want the cost of a discounted quick sale, see the piece on quick home sale trade-offs. Here the question is narrower: which route is fastest, and why.
Here is what you’ll find. First, the idea of two clocks, one for finding a buyer and one for reaching closing, and why the theoretical fastest sale rarely matches the realistic one. Then the five bottlenecks that set the pace, a matrix showing which route each one hits, and the levers sellers have to speed each route up. After that come ranked scenarios (clean title, a lien, tenants, probate, damage), a table explaining the speed-versus-net curve, and a candid look at when cash is not quicker. The article closes with preparation steps that help every route and a decision framework for matching a route to your priority.
One caution up front. Nothing here is a promise about how fast a specific buyer, company, or agent will perform. Where timelines or dollar figures appear in examples, they are hypothetical and labeled that way. Where a rule or statistic appears, it comes from a source named in the text and listed at the end, with the date checked.
Why the Fastest Way to Sell a House Depends on Your Bottleneck
The two clocks: finding a buyer and getting to closing
Time to a signed contract: price, exposure and demand
The first clock runs from the day you decide to sell to the day a buyer signs a contract you’ve accepted. For a traditional listing, that time depends on four things you can partly control (price, condition, access, and how widely the home is marketed) and one you can’t (how many qualified buyers are shopping in your price range right now). NAR reported a median time on market of 31 days for August 2026 sales, up from 29 days the month before (NAR, released September 10, 2026). That median says half of the homes that sold spent a month or less on the market, and half spent longer; it is a market-wide marker, not a prediction for any one house.
For other routes, the first clock looks different. An investor or cash buyer can often make an offer after a single walk-through or a review of photos and basic facts, which puts the time to a contract in days. A platform offer may arrive after an online submission and a property review. An auction sets its own date. And if you already know a buyer (a neighbor, a relative, a tenant, a business partner), the first clock may be close to zero, which is the one situation where a for-sale-by-owner sale can be the fastest route.
The takeaway is that the first clock rewards exposure and a price aimed at the fastest-selling band of comparable sales. It does not reward asking for a premium. A home priced above what comparable properties are selling for usually sits, and every week on the market adds to your holding costs and sometimes signals to buyers that something is wrong.
Time from contract to closing: the clock most guides skip
The second clock runs from the signed contract to the day funds move. This is where most “fast sale” claims hide their assumptions. What sets it is a list of tasks that often run in parallel: title work and payoff letters, the buyer’s inspection or due-diligence period, association documents, any lender steps (appraisal, underwriting, final approval, and a Closing Disclosure that must reach the buyer three business days before closing, per the CFPB), and finally possession and the move.
Cash contracts remove the lender tasks from that list. They don’t remove the others. Title still needs to be searched and cleared, a payoff still has to be requested, an inspection period (if the buyer wants one) still has to run, and the property still has to be empty on the agreed date. Under federal servicing rules, a mortgage servicer must send a payoff statement within a reasonable time, and no later than seven business days after a written request (12 CFR 1026.36(c)(3)), so even the simplest payoff can set a floor of more than a week on the second clock if nobody asked early.
The two clocks add up. A listing might attract an offer on day three and need 35 days to close. A cash buyer might take five days to reach a signed contract and ten more to close. Neither number tells you anything alone; the total does, along with how likely each part is to slip. That’s why a route that wins one clock can lose overall.
Fastest in theory versus fastest in practice
Why advertised timelines assume the best case
When a buyer or a website says a sale can close “in as little as” some number of days, read it as a description of the best case under the buyer’s own assumptions. The conditions behind that best case are usually these: title is clean, there’s one mortgage that can be paid off quickly, all owners are available, no homeowners association needs to produce documents, the property is vacant or can be vacated at once, the buyer already has funds, and nobody asks for an extension. When those conditions hold, a short closing is real. When one fails, the number stretches.
How common is it for one to fail? The title industry’s own data points to a lot of hidden work. A March 2026 survey study from the American Land Title Association reported that mortgage payoffs occur in more than 90 percent of transactions, that involuntary liens appear in roughly a quarter of them, that 59 percent of respondents cited obtaining releases for prior unreleased mortgages as a pain point, and that 27 percent had to obtain records in person (ALTA, March 2026). Those are survey responses from title professionals rather than a count of delayed closings, but they suggest that “clean and quick” is not the default condition of a title file.
So the useful question to ask any buyer is not “how fast can you close?” It’s “what are you assuming about my property and my paperwork, and what happens to the date if any of it is wrong?” A buyer or agent who can answer that specifically, in writing, is giving you a more reliable timeline than one who quotes a single number.
Estimating your own range: best, likely and slow
You can build a rough timeline for your own house with three cases. The best case assumes every task finishes at the quick end of its range. The likely case assumes one routine slip, such as a payoff letter taking the full seven business days or an inspection producing a small repair request. The slow case assumes a real problem surfaces: an old mortgage needs a release, an owner needs to be located, an appraisal comes in low.
The arithmetic trick is that parallel tasks overlap, so the clock follows the longest chain of dependent tasks (what project managers call the critical path), not the sum of everything. If title work takes ten days and an inspection period takes seven, and both start at signing, the earliest closing is about ten days out, not seventeen.
Illustrative example (hypothetical numbers, not market data): A homeowner has one mortgage, no association, and a vacant house. With a cash buyer, the best case is a contract-to-closing time of about 10 days, the likely case is about 17 days if the payoff letter takes its full allowance and a small title item appears, and the slow case is about 30 days if an old mortgage release has to be tracked down. With a financed buyer on the same house, the same method might give roughly 28 days, 40 days, and 55 days, because the appraisal, underwriting, and disclosure waiting period sit on the critical path. These numbers show the method, not what any buyer will do.
Once you have three cases, compare them with your deadline. If your hard date falls between the likely and slow cases, you need either a buffer, a plan to fix the likeliest problem early, or a route whose slow case is shorter. If your hard date is earlier than the best case of every route, no choice of buyer will meet it, and it’s time to look at extending the deadline, a rent-back or delayed possession, or a short-term bridge such as temporary housing.
The Bottlenecks That Set the Clock: Financing, Appraisal, Inspection, Title and Possession
Buyer-side bottlenecks: financing and appraisal
Financing and underwriting: what a lender adds to the calendar
When a buyer uses a mortgage, a second organization with its own schedule joins the transaction. A pre-approval letter shows that a lender has looked at the buyer’s finances, but the loan isn’t final until the lender completes underwriting, receives the appraisal, clears title requirements, and issues final approval. Each step can produce “conditions,” requests for another pay stub, a letter explaining a deposit, or proof of insurance. Each condition is a small delay that you, as the seller, don’t control and often don’t see.
The last gate is the Closing Disclosure. The CFPB states that lenders must provide the Closing Disclosure three business days before the scheduled closing (CFPB). Under the regulation, the consumer must receive it no later than three business days before consummation, and a new three-business-day wait is required if the annual percentage rate becomes inaccurate, the loan product changes, or a prepayment penalty is added (12 CFR 1026.19(f), text at Cornell Legal Information Institute, checked October 2026). For this timing rule, a business day counts every day except Sundays and federal legal public holidays (CFPB, 12 CFR 1026.2). The rule protects the buyer, and it also puts a floor under every financed closing: the lender’s final numbers must be ready at least three business days earlier.
A cash buyer replaces all of this with proof of funds. That’s the main reason a cash sale can be faster, and the reason it is the first route most people think of. The advantage is real but bounded, because underwriting is only one of several bottlenecks.
Appraisal: what it checks, how it delays, and when it can be skipped
An appraisal is an opinion of value, usually prepared for the lender. For a VA-guaranteed loan, the lender (not the buyer) requests a VA-approved appraiser, and the report, the Notice of Value, gives the VA’s view of the home’s value and whether it meets the VA’s minimum property requirements; the VA’s own guide adds that “an appraisal is not a home inspection” (VA Home Loan Guaranty Buyer’s Guide, checked October 2026). On FHA-insured loans, an FHA Roster appraiser signs the appraisal certification and must note deficiencies against FHA’s minimum property requirements or standards and notify the lender (HUD Mortgagee Letter 2025-18, June 2025). In practical terms, an FHA or VA appraisal can bring up property conditions, such as peeling paint, a failing roof, or a missing handrail, in addition to a number.
Conventional loans can sometimes skip the appraisal. Fannie Mae’s Selling Guide says that for certain loan casefiles its underwriting system offers “value acceptance,” in which case an appraisal is not required, but the offer depends on eligible transaction types and available prior data, excludes categories such as two-to-four-unit properties, manufactured homes, and purchase prices or values of $1,000,000 or more, and the lender decides whether to use it (Fannie Mae Selling Guide B4-1.4-10, dated June 3, 2026). You can’t count on a waiver, and you won’t know about it until the buyer’s lender does.
Two contract concepts matter here. An appraisal contingency lets the buyer renegotiate or cancel if the appraised value is below the price, within a set period. An appraisal gap is the difference between the contract price and a lower appraised value; some buyers promise to cover part of it in cash. Because a lender generally won’t lend more than the appraised value, a low appraisal shifts negotiation to you at an awkward time.
| Appraisal result | What typically follows | Effect on timeline | Seller lever |
|---|---|---|---|
| At or above contract price | Loan process continues | None beyond the lender’s normal steps | Price near recent comparable sales |
| Below contract price | Buyer asks for a lower price, brings cash, challenges the appraisal, or cancels (CFPB, VA guide) | Several days to a couple of weeks of renegotiation | Offer comps that support your price; agree on a credit or price adjustment quickly |
| Property standards flagged (FHA or VA) | Lender may require repairs and clearance before funding | Days to weeks, depending on the repair | Fix known safety and soundness items before listing |
| Appraisal not required (value acceptance, conventional only) | Lender relies on its own offer from the underwriting system | Saves the appraisal wait | None; the lender decides and eligibility limits apply |
The practical reading: pricing is the one appraisal lever you hold. A home priced well above recent comparable sales is a home most likely to run into a gap, while a home priced in line with them tends to move through this step with little drama.
Property-side and seller-side bottlenecks: inspection, title and possession
Inspection and repair negotiation: the swing period
Most contracts give the buyer a defined window to inspect the property, and the buyer chooses whether to use it. When the window closes, the buyer can generally proceed, ask for repairs or credits, or, depending on the contract, cancel. That window is the swing period of a sale. A buyer who finds nothing important proceeds on schedule. A buyer who finds a roof problem or a foundation crack opens a negotiation that can burn days, or resets the deal.
The length of the window is a negotiated term, not a legal standard, which is why cash contracts and some competitive financed offers carry short or waived inspection periods and others do not. There is one federal exception: for most housing built before 1978, sellers must give buyers a 10-day opportunity to conduct a lead-based paint inspection or risk assessment, which the parties can change by mutual written agreement and the buyer can waive (EPA, checked October 2026).
Sellers can compress the swing period by removing surprises. A pre-listing inspection, repairs to obvious safety items, and complete disclosures give buyers fewer reasons to renegotiate. The tradeoff is cost and the risk of finding something you’d rather not know, so it’s a decision to weigh, not an automatic move. If the buyer is an investor purchasing as-is, a lengthy inspection may not matter much, but the investor’s own diligence still occupies days.
Title, liens, association documents, possession and court steps
Title is the bottleneck that cash can’t buy its way around. The title company searches the record, issues requirements, and waits for payoffs and releases. Payoffs alone can take up to seven business days after a written request under the federal servicing rule cited earlier. An old mortgage that was paid but never released needs a letter from the lender or its successor. A federal tax lien may require a certificate of discharge, and the IRS asks applicants to submit the request at least 45 days before the transaction date (IRS Publication 783). Judgment and municipal liens each have their own payoff or release process under state and local law.
Association documents run on the association’s schedule. In Florida, an HOA must issue an estoppel certificate within 10 business days of a written request, and the certificate remains effective for 30 days if delivered electronically or by hand (35 if mailed) (Florida Statutes 720.30851, checked October 2026). Other states differ.
Possession is the practical bottleneck: if the house is occupied by you, a tenant, or an heir’s belongings, it can’t be handed over until the occupants leave. And court steps can overshadow everything else. In California, for example, creditors in a probate estate generally have until the later of four months after letters are first issued or 60 days after a notice of administration to file claims, and selling real property requires either “full” authority under the Independent Administration of Estates Act, after giving notice, or a court hearing when the authority is “limited” (Alameda County Superior Court, checked October 2026). Other states have their own procedures and timing. Whatever the route, a court-driven step can become the longest task on your critical path.
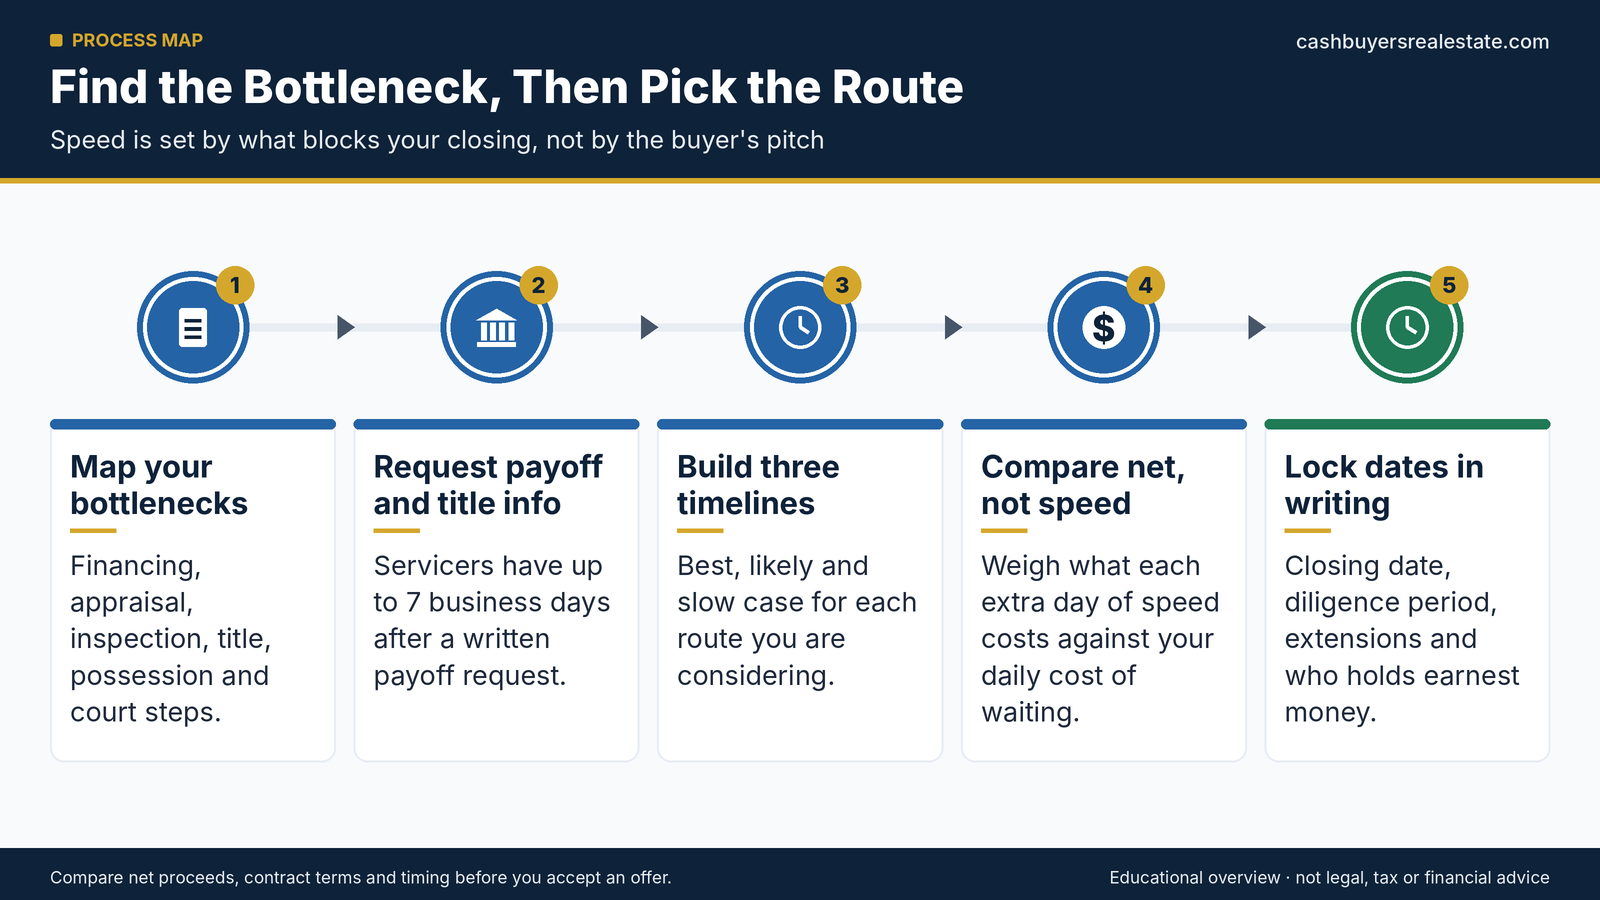
Text version of this infographic
- Map your bottlenecks — Financing, appraisal, inspection, title, possession and court steps.
- Request payoff and title info — Servicers have up to 7 business days after a written payoff request.
- Build three timelines — Best, likely and slow case for each route you are considering.
- Compare net, not speed — Weigh what each extra day of speed costs against your daily cost of waiting.
- Lock dates in writing — Closing date, diligence period, extensions and who holds earnest money.
The Bottleneck Matrix and Speed Levers for Each Route
Which route each bottleneck hits
The matrix: bottleneck by buyer type
The matrix below puts the six bottlenecks side by side with three buyer types. Read down a column to see how much of the calendar each buyer type exposes you to, and read across to see which delays are universal.
| Bottleneck | Cash buyer | Conventional loan | FHA or VA loan | Seller lever |
|---|---|---|---|---|
| Financing and underwriting | Replaced by proof of funds | Applies; lender conditions | Applies; agency rules add steps | Favor offers with strong pre-approval |
| Appraisal | No lender appraisal | Usually, unless value acceptance is used | Required; also reviews property standards | Price near comps; fix safety items |
| Inspection and repairs | Negotiated; can be short | Negotiated; buyer’s choice | Lender may require repairs | Pre-listing inspection; clear disclosures |
| Title, liens, payoffs | Applies fully | Applies fully | Applies fully | Request payoffs and releases early |
| Possession and occupancy | Often flexible by agreement | Usually at closing | Usually at closing | Be ready to vacate; negotiate dates |
| Court steps, authority, association papers | Applies fully | Applies fully | Applies fully | Resolve authority first; order documents early |
Count the rows where the cash column differs: two, financing and appraisal, plus partial relief on inspection and possession. The bottom three rows are the same for everyone.
What the matrix says about the ranking
With everything else equal, the more bottlenecks a buyer type removes, the faster the route tends to be. A cash buyer removes two outright and softens two more; a conventional buyer removes none but usually has a smoother path than a buyer using an agency-backed loan, which adds property-standards review to the appraisal. That ordering (cash, then conventional, then FHA or VA) is a reasonable default, not a law of nature. A well-qualified conventional buyer who is already pre-approved and has a quick lender can beat a cash buyer who asks for 30 days of due diligence, and a financed buyer with a large down payment and a short closing request can outrun a cash buyer who has to verify funds.
Equally important is what the matrix says about the bottom three rows: if your house has a title problem, an occupancy issue, or a court step, the route matters much less than the problem. That is why a later section looks at the cases in which cash isn’t quicker. For now, remember that ranking routes only makes sense after you know which rows apply to your property.
Speed levers by route
Levers for cash and investor sales
Sellers aren’t passive in a cash sale. A few choices tend to shorten it. Ask for a written offer that states the closing date, the due-diligence period, and who pays which closing costs, and choose the buyer whose terms match your date rather than the one with the highest headline number and the vaguest schedule. Request your payoff before you sign so the title company isn’t waiting on you. Offer to have the title company open its order the same day the contract is signed. If you expect an association package, request it right away.
A buyer’s deposit and due-diligence terms are also levers. A larger earnest-money deposit signals commitment, and a shorter, clearly bounded inspection period limits the window in which the deal can change. Shorter periods shift risk to the buyer, so expect the price to reflect it. Be careful with unusual terms: a buyer who wants an open-ended “option” period, the right to assign the contract, or a closing date “to be determined” is asking you to carry risk without a schedule. Verification steps, including proof of funds and where the deposit sits, are covered in the proof of funds explainer.
Finally, flexibility on possession is a lever in both directions. If you can vacate quickly, say so; if you need a short stay after closing, ask for it in a written occupancy agreement rather than assuming it.
Levers for agent-led sales and platform offers
For a listing, the levers are about shrinking the first clock and protecting the second. Price at or modestly below the most relevant recent comparable sales, since a home that attracts early offers can often choose among them. Prepare the property so the first weekend of showings is the best weekend. Consider a set date for reviewing offers to gather them at once. When offers arrive, weigh terms along with price: a buyer with a strong pre-approval, a sizable down payment, and a short inspection period can be worth more than a slightly higher offer with a long contingency list.
To protect the second clock, hand the buyer’s lender what it needs fast. Provide comparable sales to support your price if the appraisal comes in short, respond to repair requests before the deadline, and offer credits rather than starting repair work in the middle of a deal when a buyer is willing. Seller-paid pre-inspections and repaired safety items reduce the odds that an FHA or VA appraisal flags the property.
Platform (iBuyer-style) offers fall in between. They can remove showings and sometimes shorten the first clock, but fees, repair deductions, and eligibility vary by company and market, and the quoted speed is a company claim. Ask for the offer, the fee schedule, and the closing timeline in writing, and compare the final net with other routes. The cash sale versus listing comparison goes deeper on that trade.
Ranking the Routes Under Five Real-World Conditions
Five scenarios and the route that usually moves fastest
Clean title and a house that can be handed over on time
Start with the favorable case, because it’s the one most “fast sale” promises describe. The title shows one mortgage and nothing else, every owner is reachable, the house is empty or can be emptied quickly, and the condition is acceptable to a retail buyer. In this setting the ranking is usually: first, a cash buyer who accepts a short due-diligence period; second, a pre-approved conventional buyer whose lender has a quick turnaround; third, a listing that has to attract that buyer first; fourth, a buyer using an FHA or VA loan, which adds property-standards review.
Notice how close first and second can be. A buyer using a conventional loan with a large down payment, a strong pre-approval, and a lender that can finish in a few weeks can match a cash buyer who wants three weeks of diligence. And in a market with many buyers for your type of home, a listing can produce multiple offers within days, letting you select the one with the shortest, cleanest schedule. The cash route’s edge is real in the middle of the market but not guaranteed at the edges.
The rest of the ranking changes as the file gets messier. The table below summarizes five common conditions and what tends to happen to the order. It describes patterns, not guarantees, and it avoids day counts because real timelines depend on local offices, servicers, and the specific buyer.
| Condition | Route that usually moves fastest | Why | What can flip the ranking |
|---|---|---|---|
| Clean title, ready to hand over | Cash buyer with short diligence, or a pre-approved conventional buyer | Fewest bottlenecks remain once financing and appraisal are removed | A buyer who requests long diligence; strong local demand for a listing |
| One lien besides the mortgage (judgment, tax, contractor) | Any route once the lien payoff or release is confirmed | Lien clearance is route-neutral and sets the pace | Federal tax lien discharge request needs a long lead time |
| Tenants in place | An investor who buys occupied property and keeps the lease | Possession can’t be delivered at closing; fewer buyers can wait | Lease end date, state and local notice rules, tenant cooperation |
| Probate or estate sale | Any route, after legal authority to sell exists | Court steps and authority come before buyer selection | Full versus limited authority; whether a hearing is required |
| Damaged or heavily deferred-maintenance home | Cash or investor buyer who prices the repairs | Avoids lender property standards and repair negotiations | Insurance claim pending; code or permit issues; liens |
Read the table from the bottom up. The more of the lower rows describe your house, the less your choice of route matters, and the more the underlying problem does.
One lien, tenants, probate or damage: how the ranking shifts
A lien besides the mortgage is a timing problem that no buyer can skip. A judgment or contractor lien needs a payoff and a release; a federal tax lien may need a certificate of discharge, which the IRS asks to receive at least 45 days before the transaction date (IRS Publication 783). If your lien is the paid-at-closing kind, a cash buyer is still often fastest. If it needs a discharge, the route barely matters. The guide to selling quickly with liens covers how each type is typically resolved.
Tenants change who the realistic buyers are. A financed owner-occupant generally wants possession at closing, and a lease may prevent that. An investor who is happy to keep the tenant can close without waiting for the lease to end, which frequently makes that investor the fastest route. State and local landlord-tenant law and the specific lease control the rest, so treat any promise of a quick vacant sale with caution until you’ve confirmed the lease terms. The tenants guide goes through what applies.
Probate ranks authority above everything. Until the person selling has legal authority, no buyer can safely close. After that, the order looks like the clean-title ranking, with court-driven items layered in. In the California example cited earlier, a personal representative with full authority can sell after giving notice, while one with limited authority needs a court hearing, which can add weeks. Other states have different procedures, and the probate sale guide and the probate real estate hub give the broader view.
Damage or severe deferred maintenance shifts the ranking toward buyers who aren’t constrained by lender property standards. A conventional or government-backed buyer may not be able to close on a house that fails the appraiser’s checks, while a cash buyer can price the repairs and move on. Even then, a pending insurance claim, open permits, or liens can slow things. For this case in depth, see the piece on selling a fixer-upper quickly.
Where an agent-led sale is quickest
Conditions where a listing beats a cash offer on speed
It’s tempting to treat “cash” and “fast” as synonyms, but there are conditions where a plain listing is the quicker route. One is a strong seller’s market for your price tier, where a well-priced, clean home draws several offers inside the first week. Another is when the cash offers available to you come with long due-diligence periods, extension rights, or closing dates set weeks out, while a listing buyer can close in thirty days with a pre-approval already in hand. A third is when you need an offer to be a real, competitive process, not a single negotiation: a listing can create multiple bidders at once, and the best of them may have the shortest timeline.
There’s also a sequencing advantage. A listing agent can run an offer deadline: all offers are due by a set date, and you choose among them on one day. Compare that with calling buyers one at a time. The deadline model compresses the first clock for a home that draws interest. NAR’s August 2026 median time on market of 31 days is the market-wide marker, and a home priced to be in the faster half of that distribution can attract a contract in less than a month.
The honest limit is that a listing carries more variance. Half of sold homes take longer than the median to find a buyer, and the financed buyer’s second clock adds weeks you can’t remove. If your deadline is hard, a listing works best as one leg of a two-track plan: list, and in parallel request cash terms in writing as a backstop.
Pricing and preparation choices that shorten a listing
Most of what shortens a listing happens before the first showing. Price is the first lever. A price slightly under the most relevant recent sales tends to draw more early attention than a price slightly over, and early attention is where multiple offers come from. Condition is the second: fix safety and function problems that would trigger repair demands or an FHA or VA flag, clean aggressively, and make the home easy to see. Access is the third. A lockbox, flexible showing hours, and quick responses to buyer questions keep momentum.
Preparation also covers paper. Have the seller’s disclosure completed, the payoff requested, and association documents ordered before the contract, so that the second clock starts with several tasks already done. Where the contract allows, offer a closing date that works for a lender: thirty days is common in many financed sales, and promising less than a lender can deliver sets up an extension. The companion guide on how to sell a house fast step by step lays out the sequencing day by day, and preparing for a fast home sale covers the document side.
Speed Versus Net: What Each Day Saved Actually Costs
How the speed-price curve works
Price, time and certainty: the three levers
Every sale trades among three things: the price you receive, the time it takes, and the certainty that it closes. A buyer who offers speed and certainty must be paid for the risk and work involved, and that payment comes out of your price. An investor’s offer typically reflects the home’s value, the cost of repairs, holding and financing costs, resale costs, and a required margin, a mix that the explainer on how cash offers are calculated breaks down. A retail buyer paying full value brings a slower, more variable process in exchange.
The relationship isn’t a straight line. Logic suggests the biggest price concession sits at the very fast end, where the buyer is paying for a short timeline and taking on repairs and resale risk, and that the gain from waiting flattens once you’re already in the range where a normal retail buyer sets the price. The actual shape in your market and for your house is something only real offers can show, but the idea (steep at first, then flatter) is worth seeing with numbers, and the ladder below does that with a hypothetical house: in it, going from about two weeks to about six weeks recovers most of the gap, while going from about three months to about four recovers far less.
Certainty is the third lever and the hardest to price. A listing that falls through at week five costs weeks and often a price reduction. A cash contract with a buyer who cancels during diligence does the same. A route that is somewhat slower on paper but far less likely to fall apart can be faster in practice, which is another reason to compare ranges and not best cases.
An illustrative speed-versus-net ladder
Illustrative example (hypothetical numbers, not market data): Assume a house in average condition with clean title that a fully prepared retail sale at the market price would value at $350,000. Assumed costs: 5 percent total commission on agent-led sales (negotiable and used here only for arithmetic), 1.5 percent seller closing costs on agent-led sales and 1 percent on the cash route, $2,500 of prep on agent-led routes, and $1,100 a month in taxes, insurance, utilities, and upkeep while you own the house. The investor offer is assumed to be 82 percent of the market value. Everything here is an assumption chosen to show the curve’s shape, not a benchmark for any real market or buyer.
| Posture | Days to close | Net proceeds | Net as % of $350,000 | Extra net per added day |
|---|---|---|---|---|
| Investor cash offer, as-is (82% of value) | 14 | $283,630 | 81.0% | n/a |
| Agent-led, priced aggressively ($340,000) | 45 | $313,750 | 89.6% | about $972 |
| Agent-led, priced at market ($350,000) | 75 | $322,000 | 92.0% | about $275 |
| Agent-led, priced for patience ($357,000) | 120 | $326,895 | 93.4% | about $109 |
Here is how the arithmetic works for the two ends. The cash route: $287,000 price, minus $2,870 in closing costs and $500 in carrying cost for 14 days, leaves $283,630. The patient listing: $357,000 price, minus $17,850 commission, $5,355 closing costs, $2,500 prep, and $4,400 in four months of carrying cost, leaves $326,895. Between those two points the seller gains $43,265 for waiting 106 more days, about $408 per day on average, but the gain per day isn’t even: roughly $972 a day over the first 31 added days, then $275, then $109.
Two limits keep the ladder honest. First, it assumes the house sells at each price in each time, and real listings sometimes don’t, so the patient rows carry more risk than the table shows. Second, none of the numbers account for the value of your own time, stress, or the cost of a missed deadline. The table’s job is to show that the price of speed isn’t constant; it’s highest where the timeline is shortest.
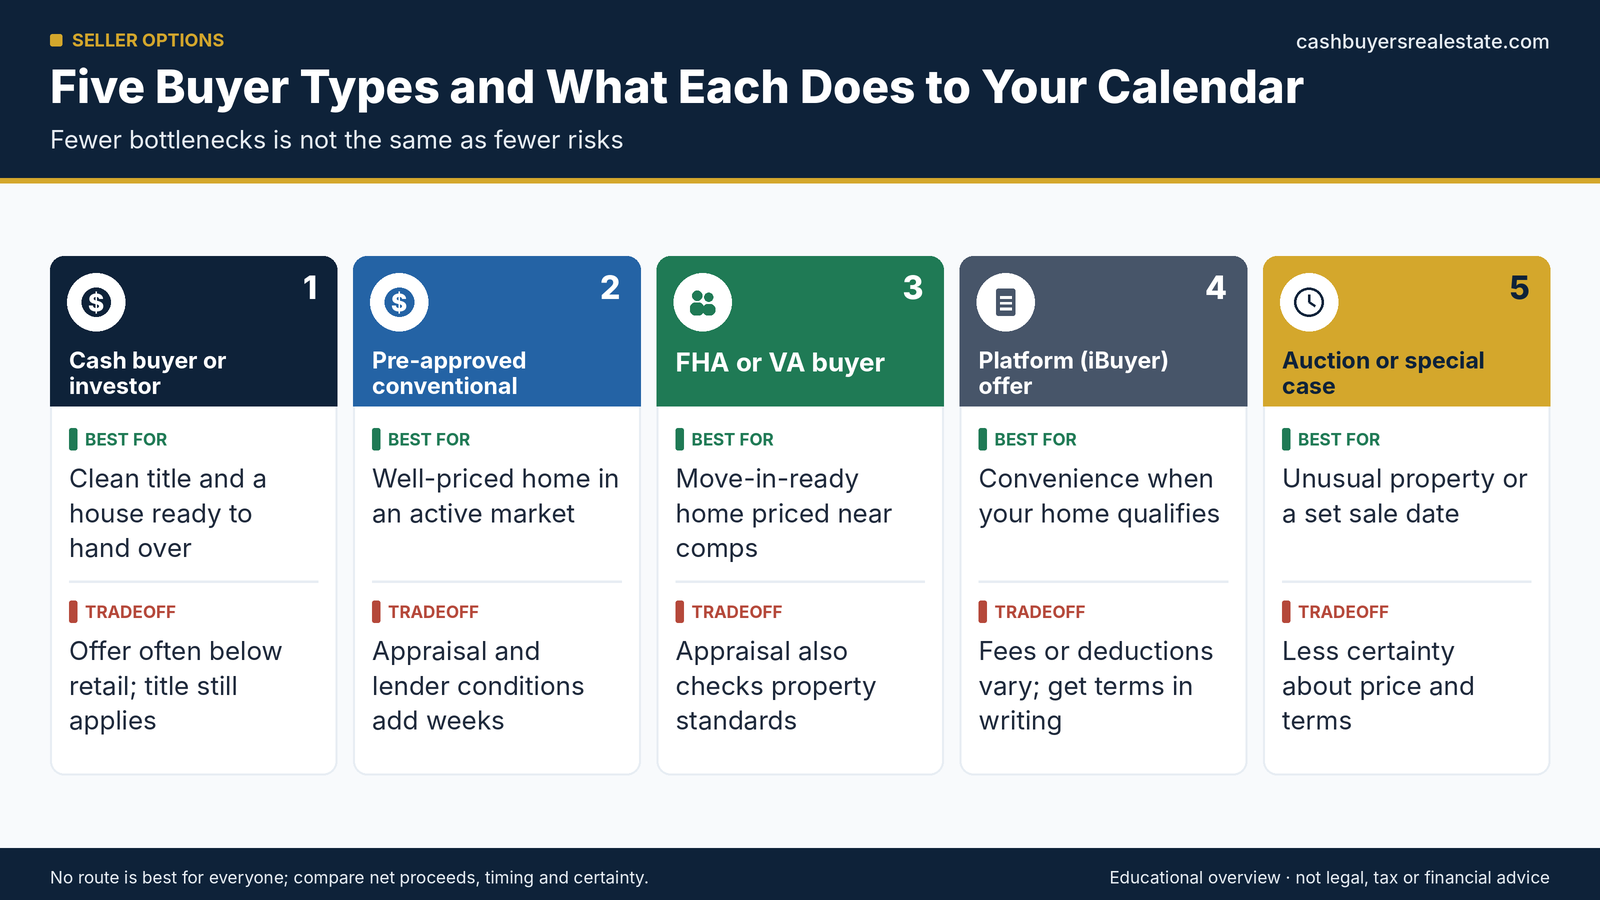
Text version of this infographic
- Cash buyer or investor — best for: Clean title and a house ready to hand over; tradeoff: Offer often below retail; title still applies
- Pre-approved conventional — best for: Well-priced home in an active market; tradeoff: Appraisal and lender conditions add weeks
- FHA or VA buyer — best for: Move-in-ready home priced near comps; tradeoff: Appraisal also checks property standards
- Platform (iBuyer) offer — best for: Convenience when your home qualifies; tradeoff: Fees or deductions vary; get terms in writing
- Auction or special case — best for: Unusual property or a set sale date; tradeoff: Less certainty about price and terms
Finding your break-even
Daily holding costs versus the price of speed
You can turn the ladder into a decision rule. Add up your real daily cost of waiting: the carrying costs of the house (in the example, $1,100 a month is about $37 a day), plus any extra cost created by the delay, such as a second housing payment, rent, a storage unit, or interest on a bridge loan. Then compare it with the “extra net per added day” in the ladder. As long as the extra net per day is higher than your daily cost of waiting, waiting pays. Once it drops below, speed is the better deal.
Illustrative example (hypothetical numbers, not market data): A seller who has already bought another home carries a second mortgage payment of $2,600 a month, or about $87 a day, on top of the $37 a day of carrying costs on the first house: roughly $124 a day. Moving from the aggressive-listing row to the market-price row earns about $275 for each added day, well above $124, so waiting pays. Moving from the market-price row to the patience row earns about $109 per added day, below $124, so the extra 45 days aren’t worth it for this seller. A different seller with no second payment, paying only $37 a day, might reasonably wait for the last row.
A few cautions apply. The break-even changes if a deadline is a cliff (a rate lock expiring, a foreclosure sale date, a job start) rather than a daily cost. It also changes with risk: the longer rows involve more chance of price cuts, and a seller who can’t absorb a surprise should weigh that. And it assumes you compare real numbers. Get actual written terms for the quick route and an agent’s written pricing opinion for the slow one before you apply any rule, and use the net proceeds calculator to check the arithmetic with your own figures.
When paying for speed makes sense, and when it doesn’t
Paying for speed makes sense when the cost of delay is concrete and larger than the price gap. Examples include a closing date tied to a purchase elsewhere, a mortgage that’s falling behind where a quicker sale protects your credit and options, a property that’s costing a lot to hold (an empty house with utilities and a leaking roof), or a family situation in which time itself is the priority. Those are real reasons, and nothing about them is shameful.
It makes less sense when the urgency is manufactured. Pressure to sign today, a countdown, or a claim that an offer disappears tonight are sales tactics rather than market facts. It also makes less sense when you have a flexible deadline and the gap between routes is large: waiting a few extra weeks can be worth tens of thousands of dollars in the ladder above. And it makes less sense when a smaller step would solve the actual problem: a short delayed-possession agreement, a rent-back, a temporary rental, or a bridge arrangement can sometimes cover a gap between closing on one home and moving into the next. The urgent home sale options guide lays out those middle paths.
When Cash Is Not the Fastest Option: Title, Ownership and Property Conditions
Title and ownership problems that slow every buyer
Liens, judgments and unreleased mortgages
A cash buyer can skip a lender. A cash buyer cannot skip a title company, and the title company’s job is to make sure the buyer receives ownership free of claims nobody has agreed to. That’s why liens, judgments, and unreleased mortgages slow cash and financed buyers alike. The usual trouble spots are a judgment entered against an owner, a contractor’s or mechanic’s lien from unpaid work, unpaid property taxes or municipal charges, a home equity line of credit that was paid down but never closed, and a mortgage paid off years ago with no recorded release.
Most liens that have a known dollar amount are handled by paying them from the sale proceeds at closing, with the payoff letter delivered to the title company in advance. That works smoothly when the creditor responds promptly. It stalls when the creditor can’t be found, the lender has merged or been sold, or the amount is disputed. In the ALTA study cited earlier, 59 percent of respondents named obtaining releases for prior unreleased mortgages as a pain point, which is a good reminder that this isn’t a rare edge case.
Some defects can’t be cleared by a payoff. A forged or improperly executed deed, an unknown heir, a boundary dispute, or an old claim that no one can locate may require a court action to establish who owns the property, often called a quiet title action. How long that takes depends on the state and the court’s calendar, and it can be measured in months, not days. If that is your situation, no route is fast. The honest advice is to talk to a real estate attorney first, and the title problems hub explains the types of defects and the usual remedies.
Cash buyers differ in how they handle these. Some will close with a known lien paid from proceeds; some will walk away from anything that needs a court. A buyer who tells you a title issue “isn’t a problem” without having had a title company review it is guessing.
Co-owners, estates and missing signers
Every owner of record generally has to sign the deed. When one owner is missing, unwilling, incapacitated, or deceased, the sale hits a wall. If an owner has died, someone with legal authority, such as an executor or administrator, has to sign for the estate, or title may need to move through probate first. If an owner is incapacitated, a court-appointed guardian or a valid power of attorney that covers real estate transactions may be needed. If an owner simply refuses, other owners in many states can ask a court to order a sale or division of the property (often called a partition action), a process that can take a long time and can be expensive.
The fixes vary: a notary appointment overseas can take days, a recorded power of attorney a few days, a court order weeks to months. What matters for ranking is that none of them depend on the buyer. A cash offer on a Monday doesn’t make an absent co-owner appear on Tuesday. The sibling guides on selling an inherited house fast and probate sales go through authority questions in more detail.
If you share ownership, make the decision to sell unanimous before you spend time on offers. Hold a short call, put the plan in writing, and agree on who signs what and who responds to the title company. A written agreement among owners can save weeks at the point where title requirements land.
Property and occupancy conditions that make cash no faster
Tenants, occupants and possession timing
Occupancy is a separate clock from title. A house with a tenant can have perfect title and still be unable to deliver possession at closing. A lease generally gives the tenant rights that a sale does not automatically end, and the specifics depend on the lease terms and on state and local landlord-tenant law, including notice periods and any local protections. For a buyer who wants to live in the house, that can mean waiting until the lease ends. For an investor happy to hold the property as a rental, it can be a nonissue, and that investor may be the fastest route available.
Other occupants complicate things as well: an adult child, a relative, a roommate, or a former partner who isn’t on the lease or the title. Removing someone who doesn’t want to leave generally requires a legal process whose steps and timing differ by state, and doing it informally can create liability. If you are considering a payment to encourage a tenant or occupant to leave (sometimes called cash for keys), put the terms in writing and have an attorney review them, because the rules differ locally.
Sometimes the better move is to align the timeline with possession instead of fighting it: choose a closing date after the lease ends, sell with the lease in place to a buyer who wants it, or agree on a short post-closing occupancy period in writing. The tenants hub and the guide on selling quickly with tenants go deeper. Whatever you do, avoid promises of vacant possession that you can’t legally deliver.
Damage, code violations and unusual conditions
Damage tends to favor cash, with caveats. A fire-damaged, water-damaged, or heavily neglected house often can’t pass a lender’s appraisal or property-standards review, so the pool narrows to cash buyers and renovation lenders. But damage also introduces slow items that cash doesn’t fix. An open insurance claim means proceeds may be owed to the mortgage lender or committed to repairs. Open permits, unpermitted additions, or code violations may need to be resolved or transferred under local rules. Some localities require an inspection or certificate before sale, and the requirements vary widely. Environmental questions, such as mold, an old oil tank, or a well and septic system that don’t meet local standards, can require testing or documentation before a buyer will close.
If a covered loss such as a fire or storm caused the damage, an open insurance claim deserves its own conversation before you pick a route. Claim payments can be issued jointly to you and your mortgage lender, and the lender may control how and when money is released for repairs. That raises a practical choice: complete the claim and repairs first and sell a repaired house, or sell as-is and decide how the claim is handled at closing. The answer depends on your policy, your lender, and the buyer, so ask your insurer and your servicer in writing before you list or accept an offer, and ask a title company or attorney how an unresolved claim affects closing.
The ranking in this case is not “cash first.” It is “buyers who can accept the condition first,” which includes cash buyers and some investors, and then a question of which of them has the shortest diligence period and a clear understanding of the house. Disclose what you know. Concealing a known defect to move faster is both unlawful in many places and a way to turn a fast sale into a lawsuit.
If the house is only moderately damaged, a retail sale after modest repairs might not be slower than a discounted as-is sale once you count the price gap and the repair time. For a closer look at those repair-versus-sell tradeoffs, see the sell house as-is guide and the piece on fixer-upper sales.
Preparing Any Route to Move Faster
Pre-work that shortens every route
Title, payoff and ownership pre-checks
The best use of your first week doesn’t depend on which route you pick. Start with the items that carry waiting periods and could surprise you:
- Day 1: Send written payoff requests to every lender on the property, including home equity lines. Remember the seven-business-day limit servicers face under Regulation Z.
- Day 1 to 2: Confirm who holds title, how, and whether every owner is available. Start any power of attorney, estate, or court steps immediately.
- Day 2 to 3: Search your county’s land records or ask a title company what a search would show. Some title companies will review a file for a seller in advance; availability and cost differ, so ask. Note any judgments, tax liens, old mortgages without recorded releases, and name mismatches.
- Day 2 to 3: Request association documents if applicable, and check local requirements for sale inspections or certificates.
- Day 3 to 5: Start any releases you’ll need: letters from old lenders, lien releases, and tax clearance. Federal lien discharges follow the IRS’s 45-day lead time.
Pre-checks are cheap compared with their value. A lien found on day 3 can be on its way to resolution by day 10; the same lien found on day 25 becomes the reason a closing slips. If you own a vacant or rarely visited property, the FBI’s Internet Crime Complaint Center warned in June 2026 about criminals impersonating owners of vacant land to sell parcels without the owners’ knowledge, and suggested asking your county recorder or clerk whether it offers alerts when a document is recorded in your name (FBI IC3 alert, June 16, 2026). It’s a small step that protects ownership before you even list.
Condition, disclosure and access pre-work
Condition-related pre-work reduces the swing period later. Complete your state’s seller disclosure form honestly and early. Decide whether a pre-listing inspection makes sense: it costs money and may reveal issues you’ll need to disclose, but it also lets you fix or price them on your terms instead of in a rushed negotiation. Get quotes for the two or three biggest repair items so you can offer credits that reflect real costs, not guesses. For pre-1978 housing, have the lead-based paint disclosure and EPA pamphlet ready.
Access is pre-work too. Make sure utilities are on, so inspectors and appraisers can test systems. Confirm that locks, gates, and garage doors work. Clear a path to the water heater, electrical panel, and attic. Gather keys, codes, and warranty paperwork. And gather the simple things buyers ask for in the first week: utility bills, tax bills, association dues, permit history, and the age of the roof and major systems.
If you can, schedule a single block of time (a morning, say) to finish the whole list, rather than letting it spread over weeks. A seller who answers every buyer or title question within a day tends to shave days off the second clock.
Protecting speed from late-stage threats
Re-trades, extensions and fall-throughs
The final stretch is where speed gets lost to renegotiation. A buyer may ask for a price cut after the inspection, request an extension to arrange financing, or propose a new closing date. Some of these requests are legitimate, and some are tactics. A few habits help you tell the difference and protect your timeline. Know your contract’s deadlines and consequences before a request arrives, including whether time is of the essence, a clause common in contracts that makes the stated dates strictly enforceable. Ask for any extension request in writing, with a specific new date and what the buyer is offering in return, such as additional earnest money. And keep a documented timeline of what’s been requested and delivered by each side.
It also pays to have a backup. If you receive more than one offer, consider keeping the second-best buyer informed, or ask your agent whether a backup offer clause is appropriate. If the sale falls through, a warm second buyer can save weeks. Be careful with last-minute price changes from buyers who appeared flexible earlier: they don’t prove bad faith, but they warrant checking the buyer’s funds, the closing partner, and the reasons given. The scam prevention guide lists the patterns to verify.
Earnest money is worth understanding before you need it. It is a deposit the buyer places with a title company, escrow agent, or attorney after the contract is signed, and the contract says when it is refundable and when it is forfeited. A larger deposit with tight refund conditions signals a committed buyer; a tiny deposit that is refundable for any reason almost until closing signals a buyer who can walk away cheaply. Neither is wrong, but they imply different risks to your timeline, so weigh the deposit and the conditions together with the price.
One more habit: do not commit your own next step so tightly to the contract date that a one-week slip becomes a crisis. Flexible movers, a short-term rental option, and a conversation with your next landlord or seller about extensions cost little and protect you from the most expensive kind of delay, the kind with no plan B.
Wire fraud and closing-day safeguards
Faster timelines raise fraud risk because everyone is rushing. The CFPB’s guidance for closings is to agree in advance on two trusted people who can confirm the closing process and payment instructions, write down their phone numbers now, never follow instructions in an email without confirming, be wary of last-minute changes to wiring instructions, and never email financial information (CFPB blog, June 2019, archived). If you think you’ve sent money to the wrong place, the CFPB advises contacting your bank or wire-transfer company immediately and asking for a wire recall, then filing a complaint with the FBI’s IC3.
As the seller, your risk is mostly about your own proceeds and about identity. Give your bank details to the closing agent by phone or in person where possible, and confirm receipt instructions by calling a number you found independently, not one in an email. Be cautious about last-minute emails that claim to come from your title company. And check that the person you’re dealing with can be verified through a state licensing lookup or a business registration.
Closing day itself should be dull. If anything surprises you, a new fee, a changed payee, a different closing agent, pause and call the title company at a number you trust. A short delay costs far less than a misdirected wire. The cash home sale process guide walks through what a normal closing looks like so you can recognize an abnormal one.
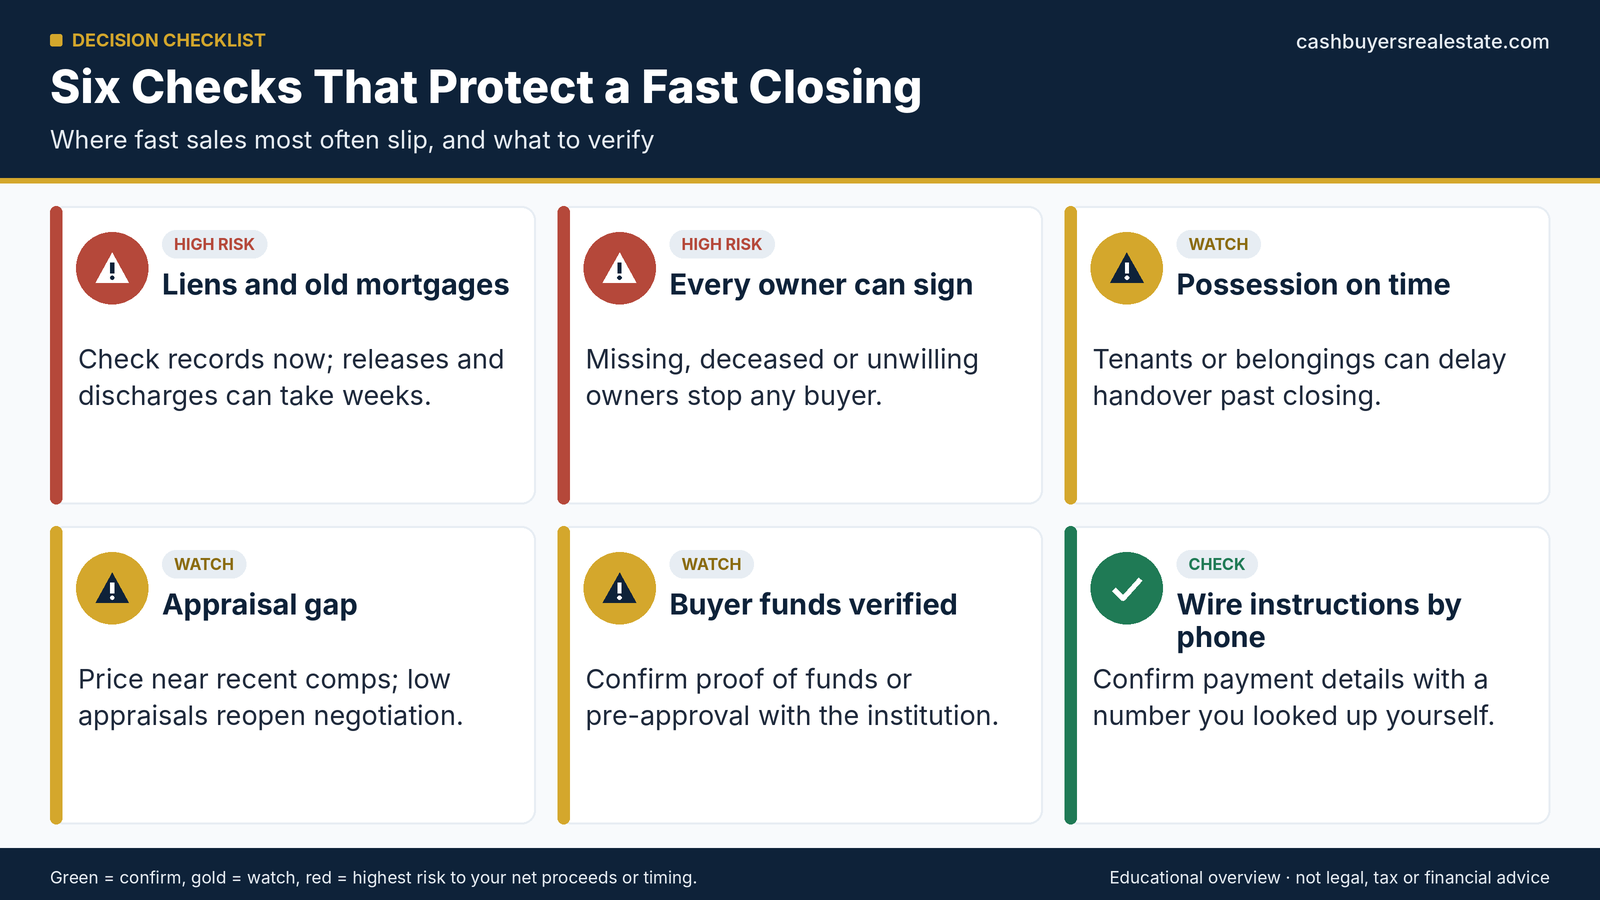
Text version of this infographic
- Liens and old mortgages — Check records now; releases and discharges can take weeks.
- Every owner can sign — Missing, deceased or unwilling owners stop any buyer.
- Possession on time — Tenants or belongings can delay handover past closing.
- Appraisal gap — Price near recent comps; low appraisals reopen negotiation.
- Buyer funds verified — Confirm proof of funds or pre-approval with the institution.
- Wire instructions by phone — Confirm payment details with a number you looked up yourself.
Frequently Asked Questions About the Fastest Way to Sell
Questions about routes and delays
Questions about which route is fastest
- Is a cash sale always the fastest way to sell a house?
No. A cash sale removes financing and the lender’s appraisal, which are two of the six common bottlenecks, but title work, payoffs, association documents, possession, and court steps still apply. If your title is clean and the house is ready to hand over, cash is often the quickest. If you have a lien, a tenant, or an estate to settle, the problem rather than the buyer sets the pace.
- What is the fastest a house can realistically sell?
There is no single number, because it depends on the file. The shortest closings happen when title is clean, one payoff is requested early, all owners are available, the buyer has verified funds, and the contract allows a short diligence period. Even then, a servicer can take up to seven business days to send a payoff statement after a written request, so a two-week closing is a best case, not a baseline. If a buyer quotes something shorter, ask which of those conditions they’re assuming and what happens to the date if one of them fails.
- Can a platform or iBuyer offer close faster than an investor?
Sometimes, sometimes not. Platform offers can shorten the first clock by skipping showings, but fees, repair deductions, eligibility, and closing timelines vary by company and market. Ask for the offer, the fee structure, and the expected closing window in writing, and compare the final net with other routes rather than the speed claim alone.
- Is an auction a fast way to sell?
An auction can fix the day of the sale, which gives certainty about when bidding ends. Closing terms, deposits, buyer’s premiums, and reserve prices vary by auction company, and the price is whatever the bidding produces. That makes auctions better for unusual properties or special situations than for sellers who need a particular minimum net on a particular date. If you’re considering one, ask whether a reserve price protects your floor and how soon after the auction the buyer must close.
Questions about bottlenecks and delays
- What most often delays a closing?
On the buyer’s side, lender steps and appraisal issues; on the property side, title and lien clearance, repair negotiations, association documents, and possession. The ALTA study cited earlier suggests that payoffs are involved in more than 90 percent of transactions and that unreleased prior mortgages are a common headache. Starting payoff and title tasks in week one is the most reliable defense, followed by pricing the home in line with recent comparable sales so the appraisal step has less room to go wrong.
- Can a low appraisal be fixed quickly?
Sometimes. The CFPB notes that an appraisal below the price is strong evidence the price was above market value and suggests asking the seller to lower the price. For VA loans, the VA guide lists options such as asking for a Reconsideration of Value with additional sales data, renegotiating, or bringing cash to cover the difference. Each path takes days, and pricing your home in line with recent comparable sales makes the problem less likely.
- Does an as-is sale skip the inspection?
Not by itself. “As-is” usually describes who pays for repairs, and buyers can still inspect and decide whether to proceed or renegotiate, unless they voluntarily waive the inspection. Disclosure obligations also remain, and they vary by state. For most pre-1978 homes, federal law requires lead-based paint disclosures and a 10-day inspection opportunity unless the buyer waives it.
- How long does a payoff statement take to arrive?
A servicer must send it within a reasonable time and no more than seven business days after receiving a written request from you or someone acting for you (12 CFR 1026.36(c)(3)). Many arrive faster, and a title company can request one for you once there’s a contract. Ask for a per-day interest amount so the figure can be adjusted if closing moves, and ask how long the quoted payoff figure stays good, because it is calculated through a specific date.
Questions about money, risk and special cases
Questions about price and net
- How much less will a fast sale net me?
It depends on the house, the buyer, the market, and your costs, so no honest single figure exists. The hypothetical ladder earlier shows the shape of the trade-off, not a prediction. The reliable method is to get written terms for the quick route and an agent’s written estimate for the slower one, then compare net proceeds after commissions, closing costs, repairs, and holding costs.
- Will I owe a commission on a cash sale?
Not necessarily. Many direct purchases by investors involve no agent, so no commission. But if you’ve signed a listing agreement and a cash buyer purchases the property during the listing term, the agreement’s terms control what you owe. Commissions are negotiable. Read the fine print before signing, and ask about what happens if you sell to a buyer you find yourself. Those terms are easiest to change before you sign, not after a buyer appears.
- Can I list the house and also ask for cash offers?
Often, but check the listing agreement first. Some agreements give the agent a commission regardless of who finds the buyer, while others carve out named buyers. Running both tracks is a common way to compare, as long as you know what you’d owe under each outcome and haven’t signed something that blocks it.
- Could taxes change my timing?
Possibly. For a main home, the federal exclusion of up to $250,000 of gain ($500,000 on a joint return) generally requires that you owned and used the home as your main residence for at least two of the five years before the sale (IRS Topic No. 701). If you are close to that line, a few weeks can matter. Because your situation is specific, a tax professional is the right person to confirm it.
Questions about safety and special situations
- How can I tell whether a quick offer is trustworthy?
Verify rather than judge. Ask for proof of funds and confirm it with the institution using a phone number you looked up, check that earnest money goes to a title company or attorney, read the full contract for dates and assignment language, and confirm the closing agent is licensed and reachable. Pressure to sign today or last-minute changes deserve a pause. The proof of funds guide and the scam prevention guide go through each step.
- What if I’m trying to sell before a foreclosure?
Contact your servicer early, because options and timelines depend on your loan and your state. HUD-approved housing counselors, found through the CFPB, can provide independent advice on defaults, forbearances, and foreclosures, often at little or no cost. A sale can be one of several options, and the foreclosure hub covers how it compares.
- Does a vacant house sell faster?
It solves the possession problem, and it makes showings and inspections easier. But vacancy brings its own costs and risks: utilities to maintain, security, and insurance terms that can differ for unoccupied homes, which you should confirm with your insurer. The vacant property guide covers those tradeoffs.
- Can I sell quickly if I still owe a mortgage?
Yes. Most sales pay off the mortgage from the proceeds at closing, which is why the payoff request matters. The question is whether the sale price covers the payoff plus costs; if it doesn’t, you’d need to discuss options with your lender. The guide to selling fast with a mortgage walks through the mechanics.
Matching Your Route to Your Bottleneck and Taking the Next Step
A decision framework by situation
Decision matrix: situation, where to start, what to run alongside
The right starting point is the route that handles your biggest bottleneck, with a second route running in parallel as a comparison or a backstop. The matrix below sorts common situations. It’s a framework for thinking, not a ruling, and your numbers and constraints should override it.
| Your situation | Start with | Run alongside | Watch for |
|---|---|---|---|
| Clean title, firm close within about three weeks | Written cash terms with short diligence | A listing plan for comparison | Vague schedules; extension rights; verify funds |
| Clean title, six to ten weeks, net matters most | Agent-led listing priced to draw early offers | One written cash offer as a benchmark | Appraisal gap; long contingency lists |
| A lien beyond the mortgage | Payoff and release work immediately | Buyers who can close once the lien is cleared | Creditor response times; IRS discharge lead time |
| Tenant in place | Investor buyers who accept the lease | A listing timed to the lease end | Notice rules; promises of vacant possession |
| Estate or probate sale | Establish legal authority to sell | Gather offers while the court process runs, if allowed | Full versus limited authority; court hearings |
| Damaged or heavy-repair home | Cash or investor buyers who price repairs | A repair-then-list estimate | Pending insurance claims; open permits; hidden defects |
The row you land in tells you what to do first, not what the outcome will be. If you land in two rows, address the harder one first, since it determines the earliest possible closing for everyone.
A short self-assessment: five questions that point to your route
- Does every owner agree, and can each one sign? If not, resolve authority before anything else.
- How many payoffs and liens sit on the title? One mortgage is routine; more than that, or any tax lien, extends the timeline and decides which buyers are realistic.
- Can the house be handed over on a set date? If occupants or belongings stand in the way, possession is your bottleneck.
- Would a retail buyer’s lender accept its condition? If you suspect not, as-is buyers move to the front of the line.
- What does one more week of waiting cost you in dollars? Use that figure with the ladder logic from earlier to decide how much speed is worth paying for.
Answering these five questions honestly takes about fifteen minutes and usually points to one or two routes worth testing. If your answers are mostly “yes,” the choice between cash and listing is largely about price and preference. If several are “no,” your first call should be to a title company or attorney, not to a buyer.
Illustrative example (hypothetical numbers, not market data): A homeowner needs to close within 30 days. Title shows one mortgage and one $12,000 contractor’s lien from a past project. The owner uses the five questions: everyone can sign (yes), two payoffs (so title will take longer than a single-mortgage file), the house is vacant (yes), a retail lender would accept its condition (yes), and the cost of waiting is modest. The three-case method gives a cash route of roughly 12, 20, and 35 days, because the contractor’s lien release is the item that might drag, and a financed route of roughly 30, 42, and 60 days. With a 30-day deadline, neither route’s likely case fits unless the lien is resolved right away, so the first move is to contact the lienholder for a payoff and release on day 1. Only after that does the choice between cash and a listing matter.
What to do next
The first seven days, ordered by what takes longest
- Day 1: Request payoffs in writing from every lender. Write down your hard date and your minimum net.
- Day 1 to 2: Confirm all owners and signers. Start any authority paperwork.
- Day 2 to 3: Check county records for liens and judgments, and ask a title company what a search would show.
- Day 3: Build your three-case timeline (best, likely, slow) for each route you’re considering.
- Day 3 to 5: Request written terms from buyers and a written pricing opinion from an agent. Ask for proof of funds, dates, diligence periods, and costs.
- Day 5 to 6: Compare net proceeds and the slow-case timeline of each option against your deadline.
- Day 7: Choose a route, line up your closing partner, and calendar every contract date.
If you’re short on time, the first three items are the ones that run in the background while you do everything else. They are also the cheapest to start, which is why they come first. Keep a one-page tracker with each task, the person responsible, the date you asked, and the date you expect an answer. When something slips, the tracker shows which downstream date moves with it, and you can tell the buyer, agent, or title company before they have to ask.
Questions to ask any buyer, agent or platform about timing
- What are you assuming about my title and my paperwork, and what happens to the closing date if those assumptions are wrong?
- Is the closing date in the contract a fixed date, or “on or before,” and who can extend it?
- How long is the due-diligence or inspection period, and what can the buyer do at the end of it?
- If a loan is involved, what are the appraisal and financing contingency dates?
- Who holds the earnest money, how much is it, and when is it refundable?
- What costs will come out of my proceeds, and which of them are fixed versus estimated?
- If I need a few extra days in the house after closing, can that be written into the contract?
These questions work on any route because they target the same thing: the difference between a timeline someone quotes and a timeline someone commits to in writing. A buyer or agent who gives specific, documented answers is easier to plan around than one who tells you not to worry. The bottom line is that the fastest way to sell a house is the route that fits your house’s real bottleneck, supported by early paperwork and offers compared on net proceeds, not only on speed.